Part one of three. The buyer’s half of the AI exchange, what it is made of, and where the return goes missing.
Most organizations are accounting for AI as a productivity gain. The change is bigger than that. AI changes where business capability lives, who controls it, and who is accountable for what it produces. The technology is not where the value goes missing. It goes missing on the demand side, in the buyer’s half of the exchange, which most firms have never examined. This piece defines the demand side, lays out its parts, and shows where the return goes missing.
Written for CEOs, COOs, CFOs, and boards. It assumes no technical background and offers no implementation advice.
Ask ten executives what they bought when they bought AI, and nine will answer in the language of speed. Faster drafts, faster code, faster analysis. That answer is not wrong. It is just answering a smaller question than the one their business is actually facing. Most boards are budgeting against the smaller one anyway.
The story everyone is telling
Every AI vendor sells efficiency, because efficiency is easy to measure and easy to sell. Time saved. Tickets closed. Words drafted, code shipped, output per person. Leadership buys the same story because it fits neatly into a line item: the same work, done faster, for less. The finance team can model it, the board can approve it, and everyone can point at a number next quarter.
It is not a false story. Work genuinely does get faster, and the savings are real enough to show up in a report.
But productivity only ever answers one question: how do you do the work you already do, better? It takes the shape of the business as given and asks how to run it more efficiently. That is a legitimate question. It is just not the question this technology is posing.
The question underneath is what kind of business you are becoming while you optimize the one you have:
- Where will capability live?
- What will you own outright and what will you rent, on terms someone else sets and changes?
- Who is accountable for an outcome when no person produced it?
- And how much of the value created will your business actually keep, rather than hand to a supplier or compete away in price?
Those are not technology questions. They are questions about the firm’s operating model, and almost nobody is budgeting for them.
What the demand side of AI actually is
I want to define the term precisely before going further, because it does all the work in this argument and is routinely misused to mean a market segment.
A family can buy an espresso machine to make barista-style coffee at home. But the machine is only half the exchange. The family still has to know what good coffee tastes like, decide which supplies and servicing it will depend on, develop the recipes and routines that turn the machine into drinks people want, and learn to use the machine well enough to change the household’s habits. The seller provides the capability. The buyer has to create the conditions in which that capability becomes useful.
Buying AI works the same way. The organization’s half of the exchange has several parts, and the definition below names them. That half is the demand side, and it is the half nobody sells you.
The demand side of AI is the buying organization's half of an exchange in capability it did not build. It includes what the firm can see, where the capability lives, what the firm builds around it, how quickly it can absorb it, what it keeps, and where that leaves it. It is also what the firm has given up without ever deciding to.

It is not a buyer category. It is not procurement. It is not a technology function. It is the set of things the buyer brings to the exchange, and the open question of which of them it still owns.
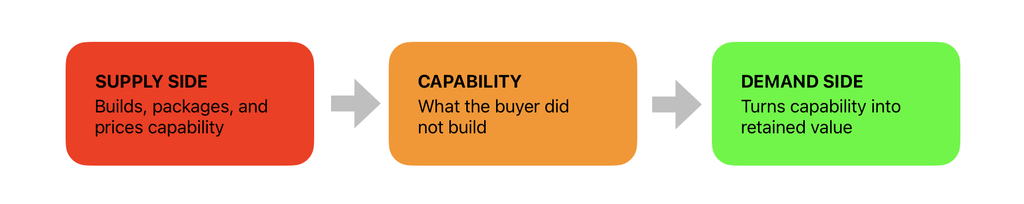
The supply side provides the capability. The demand side determines what happens when that capability enters the business, and how much of its value the buyer retains.
Three things that follow
Three things follow from that definition, and each is a position, not an observation.
- First, the demand side is made up of separate parts, each with its own logic. A firm can be strong in one and exposed in another, and the two will not show up in the same report.
- Second, those parts do not move together. A firm can retain its data while losing control of how it interprets that data. It can retain its people while losing the layer that connects them to what it bought. A firm that feels broadly in control is usually reasoning from the part it happens to measure.
- Third, control is usually surrendered by default rather than by decision. It happens through a setting nobody examined, a tool adopted one department at a time, or a dashboard accepted because it came with the product. Nobody has to behave badly for any of it to happen.
One caveat belongs here rather than at the end, because without it the rest reads as an argument for self-sufficiency. It is not. Firms rent buildings, lease equipment, and buy services because suppliers provide them better, and refusing to rent is its own expensive failure. The issue is never whether something is owned or rented. It is whether the firm made the choice and understood the terms that came with it. If the organization does not decide, defaults and suppliers decide instead, which is still a choice, just one with no owner.
Two consequences are worth naming up front. The first is that nobody outside your walls can define the demand side for you, not because external help is worthless but because the raw material is your workflows, your customer commitments, your judgment calls, and your risk appetite. No one else has those at sufficient resolution.
The second is that this is where the economics get decided. The supply side is largely settled in ways no individual enterprise can influence. The demand side is contested, mostly unattended, and it is where every dollar of return is either realized, transferred to a supplier, or never made at all.
Six parts of the demand side
These are ordered so that each one gives you what the next one needs. Start with what everything else rests on.
What you can see
Every organization runs on facts about itself. How long that process takes. How often it goes wrong. What it costs to serve a customer.
Someone decides what those facts are. Someone chooses what gets counted, on what unit, and what counts as normal. When a firm buys capability, that choice often arrives with the product. The tool reports what the supplier built it to report, and the firm reads a picture of its own operation, drawn by a party with a commercial interest in how that picture looks.
The machine keeps its own record. It counts shots pulled, water used, and cycles since the last clean, and it offers that as an account of how the household is doing. None of those numbers says whether anyone liked the coffee, whether the person who wanted a cup at seven actually got one, or whether the family now spends more on beans than it used to spend at the café. The machine is not lying. It is reporting the facts it was built to report, and those are facts about the machine.
A household that never asks what else it might have counted ends up managing to the machine’s account of itself.
This is not the same as asking what the work should be measured on. That is a fair question, and part three takes it up. But this is the question underneath it: which facts exist to be measured at all, and whose account of the operation are they?
A firm can run a perfectly sound set of measures over an instrument it did not author and never see the difference from inside.
Everything else here depends on it. A rate you cannot observe is a rate you cannot manage. A gain you cannot trace is a gain you cannot prove you kept.
Where capability lives
For most of the last thirty years, knowledge-work capability sat firmly on one side of the ledger. It lived in people. You hired them, paid them by the year, trained them, promoted them, and lost some of them to competitors. Expertise walked in the door each morning and out again each evening. It was a labor cost, and that assumption is built into nearly every management practice you have, from headcount planning to succession to span of control.
That is what changes: not simply the cost of the work, but the structure of where capability sits. A firm now holds capability in three forms, and they behave very differently.
- Owned. Proprietary workflows, institutional data, evaluation systems, codified operating knowledge, the specifications that make a system do your work rather than generic work. This form is an asset. It appreciates with use, and a competitor can’t buy it.
- Rented. Models, compute, interfaces, platforms. Held on someone else’s terms, at prices they set and change, with capabilities they can restrict, reprice, or retire.
- Employed. People in changed roles: defining the work, handling what the system cannot, owning outcomes, and supplying the judgment nobody has managed to specify.
The point is not that one is better. The point is that they move differently, and confusing them is how a firm gets surprised. Rented capability can change on a decision you are not part of. People change slowly and visibly, and they usually leave with some warning. And owned capability is the only one that gets more valuable over time, and it does that only while the firm still knows how to run it.
A firm that has never decided its mix does not have no mix. It has one it acquired department by department, which is a portfolio nobody is managing.
If a company announced it was moving a substantial share of its production capacity from owned facilities to leased ones, no board would treat that as an operational detail. It would ask about terms, dependencies, concentration, counterparty risk, pricing exposure, and the cost to reverse. A comparable shift is now underway in knowledge work, and most organizations track it as a decentralized software budget, approved department by department.
What you build around it
Bought capability does not do your work. It does generic work. Something has to sit between the two.
Something has to put the capability to work. Something has to connect it to your data, your records, your systems. Something has to decide which of your people can use it, for what, and with what permission. None of that comes in the box, because none of it can. It is made of your business.
The machine does not make your household’s coffee. It makes coffee. What turns it into your household’s coffee is everything around it: which beans you buy and where you buy them, the grind you settled on after a month of adjusting it, the order the morning runs in, the fact that the ten-year-old is allowed to press the button but not to change the settings, and what everyone does when it starts making a noise it has not made before. None of that arrived with the machine. It is made of your family.
My research calls that layer the harness. It is built from things you own, and it exists only because of things you rent, which makes it the seam between them.
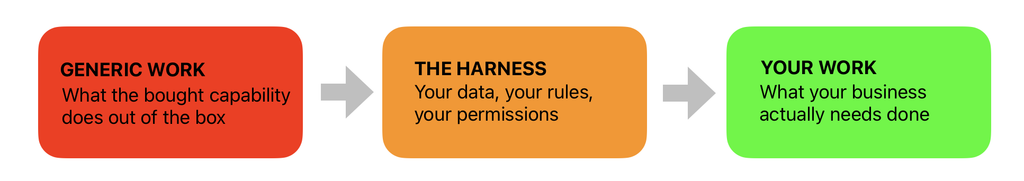
The capability does generic work. The harness is what makes it do yours, and none of it comes in the box.
It is also the most contested thing in the exchange, and the naming argument in part three is really about this layer. Whoever writes it controls the rules that describe how your business actually operates. A firm that does not author its harness does not go without one. It inherits the supplier’s, along with rules about its own work that it did not write and cannot amend.
There is a version of this the manufacturer will happily supply. Take the subscription and it ships the beans, sets the grind, pushes the recipes, and decides which of them you can still make. The coffee is fine. What the household has lost is any account of why it does things the way it does, and any ability to change supplier, because the routine now belongs to the machine.
This is also where what the firm can see gets settled. A buyer that does not author its harness does not author its own facts.
How fast you can absorb
Capability can arrive faster than an organization can use it.
The machine arrives with its full capability on day one. The household does not. Someone has to learn how to use it, find beans everyone likes, work cleaning into the routine, and make enough room in the morning to prepare coffee at home. Until those changes happen, much of what the machine can do sits unused. Buying a better machine would not make the household change any faster.
That is absorption capacity. It is not what the machine can do. It is the rate at which the household can change around it and put its capability to use. A morning when nobody can use the machine is simply a morning in which its capability produces no value. That unused opportunity does not accumulate for later.
The same limit exists inside a firm. Its absorption capacity is the rate at which it can turn delivered capability into changed work. What bounds that rate is not what the capability can do. It is how quickly the firm can redesign, govern, and staff the work around it.
It is a rate and not a stock. The rate can be increased, allocated across competing changes, left underused, or exceeded. When it is exceeded, redesign slows, decisions queue, and capability arrives faster than the organization can use it.
This limit belongs to the organization, not the capability it bought. That is why two firms can buy the same capability and produce very different results.
The failure it names is committing against capacity you assumed rather than capacity you established. Roles are taken apart on the expectation that something will put the work back together, and the reassembly arrives late or not at all.
Absorption capacity is also what builds the harness. A firm without enough of it does not avoid that layer. It inherits it.
What you keep
A gain can be created and not retained. Those are separate events.
A café buys the same machine. It lets the staff make more drinks in less time and at a lower cost per cup. The gain is real, but the café may not keep it. If the machine requires expensive supplies or servicing, part of the saving passes back to the supplier. If every competing café buys the same machine, faster service becomes normal and customers pay no more for it. If the supplier later raises its prices, still more of the gain moves out of the café.
The machine can perform exactly as promised while the café’s margin barely changes. That is the difference between creating a gain and retaining one. It is how a program can deliver everything it promised and leave the firm no better off.
What you keep is what remains after the gain has been passed to a supplier, competed away by rivals doing the same thing at the same time, or repriced by the market.
This sits deliberately outside the question of how work gets designed and run. An operating model covers that question and not this one. Pricing, margin, and share of the gain sit on this side of that line. Part two turns on that distinction.
Where that leaves you
The next round is the next moment when the terms can move: a contract renewal, a price change, a capability upgrade, supplier consolidation, or the need to switch. The question is what position the firm carries into that moment. Who are its counterparties, how many genuine alternatives remain, how costly would it be to leave, and did anything that improved today’s return reduce tomorrow’s leverage?
The manufacturer offers a better price on beans if the household commits for two years. The saving is real and it arrives every month. So does something else. The family stops pricing other beans, stops buying from anyone else, and comes to treat the subscription price as what coffee costs. When the two years are up, nothing on the bill has gone wrong. There is simply nobody else in the conversation, and no independent measure of whether the price is a good one.
What you kept and where that leaves you can move in opposite directions, which is exactly why they are two parts and not one. A cost saving can land in full while the supplier that provided it consolidates or becomes harder to replace. Capture improves, and standing degrades in the same event. A firm watching only the savings reads that as unambiguously good news.
Giving up the harness creates the same exposure without adding another name to the supplier list. The firm’s workflows, rules, and connections become organized around something it does not control. The dependency remains largely invisible until terms change or the firm tries to leave, which is precisely when its lost leverage becomes visible.
The shortfall between what was available and what you kept
A single measure runs across all six. Call it the shortfall: the gap between the gain a change in capability made available and the gain the organization actually retained.
The important part is what it does not assume. A shortfall does not require that the gain was ever produced. It is measured against what was available, not against what was delivered.
That is why I no longer call this a leak. Earlier versions of this argument did. Leakage implies something existed and escaped. Much of what this describes is a gain that was never made in the first place, and the word quietly made the problem sound more like theft than absence.
A shortfall can open at three points, and each is a different failure with a different owner.
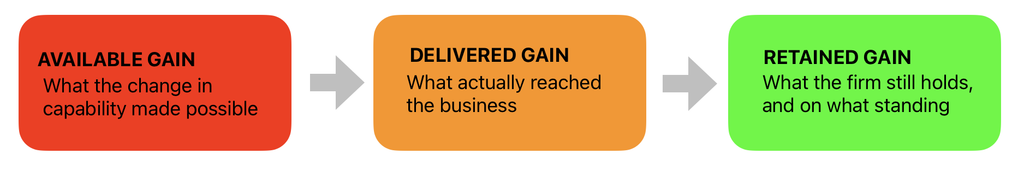
The gain narrows at each step. The shortfall is the gap between the first box and the last.
| Where it opens | What happens | The question it raises |
|---|---|---|
| Delivery shortfall | Available to delivered. The gain is never produced, so nothing reaches the boundary | How the work is designed and run |
| Retention shortfall | Delivered to retained. The gain is produced and does not stay | What you keep |
| Standing shortfall | Retained, and into the next round. The gain stays and the standing that produced it degrades | Where that leaves you |
In a delivery shortfall, the capability never produces the available gain: a step gets faster, and the process does not, or additional output creates equivalent work somewhere else. Nothing reached the boundary, so nothing was retained. This one is not a demand-side failure at all. It fails because of how the work is designed and run, and that’s why parts two and three exist.
In a retention shortfall, the gain is produced and does not stay. It passes to a supplier, to customers, or to competitors rather than remaining with the firm.
In a standing shortfall, the gain stays while the standing that produced it degrades in the same event: switching becomes harder, alternatives fewer, a supplier more powerful. Capture improves and position worsens at once, and a firm watching only the saving reads that as good news.
They are worth separating because they answer different questions. Only the second asks about the money. The first asks how the work is built, and the third asks about the next negotiation.
This measure cannot, on its own, establish what the available gain actually was. That is a counterfactual, and it is almost never calculated. Where the instruments are inherited, the reference point is supplied by the party whose product produced the shortfall. That is the sharpest reason this measure begins with what the firm can see.
Seven ways the shortfall opens
These are stated as things to watch for, not as things that have been shown.
Four of them are delivery shortfalls, where the gain never arrives.
A step gets faster, and the process does not, because the constraint sat somewhere else.
Output rises, and so does the work of checking and correcting it. That work moves to more expensive people, and the delivered result barely changes.
Time comes back in small pieces across many people and never assembles into anything a customer or a P&L would recognize.
The old roles, approvals, and measures stay exactly as they were, and a new cost is added on top.
Two are retention shortfalls, where the gain arrives and leaves.
Consumption pricing absorbs it, and the firm is more productive and no more profitable.
Rivals get the same efficiency at the same time, and the surplus passes to buyers as lower prices. Nobody does anything wrong, and the gain still goes.
And one is a standing shortfall, where the gain stays and the ground shifts.
Tools get adopted one department at a time with no rule about what may connect, so the set of dependencies is acquired rather than chosen. Dependency is not the failure. Undecided dependency is.
A delivery shortfall in two firms
Both ran into the first of the seven: a step gets faster, and the process does not, because the constraint sat somewhere else. A firm puts AI into a claims workflow. Drafting and summarization time falls sharply. Every adoption metric is green: usage is high, satisfaction is good, the pilot is declared a success and scaled. End-to-end cycle time does not move, because nobody touched the multi-stage sign-off above the drafting step. The firm bought speed and kept the queue.
Or take a professional services firm that accelerates proposal production. It now produces more proposals, of similar quality, at lower marginal cost. Win rate is unchanged, because win rate was never a function of proposal volume. The firm has industrialized an activity that was not the constraint on its growth.
In both cases, the local efficiency is real, measurable, and auditable. The enterprise return is close to zero. Nobody stole anything. The gain simply never reached the boundary where anyone would have counted it.
Both firms could have run any audit you like on their own performance and passed it. The measurements were accurate. Neither had an account of the work that ran end to end, and that is the only place where a gain either reaches the enterprise or does not.
That is the delivery shortfall part two is about. Before a firm can hold onto a return, something has to produce it, and nothing in a purchase does.